
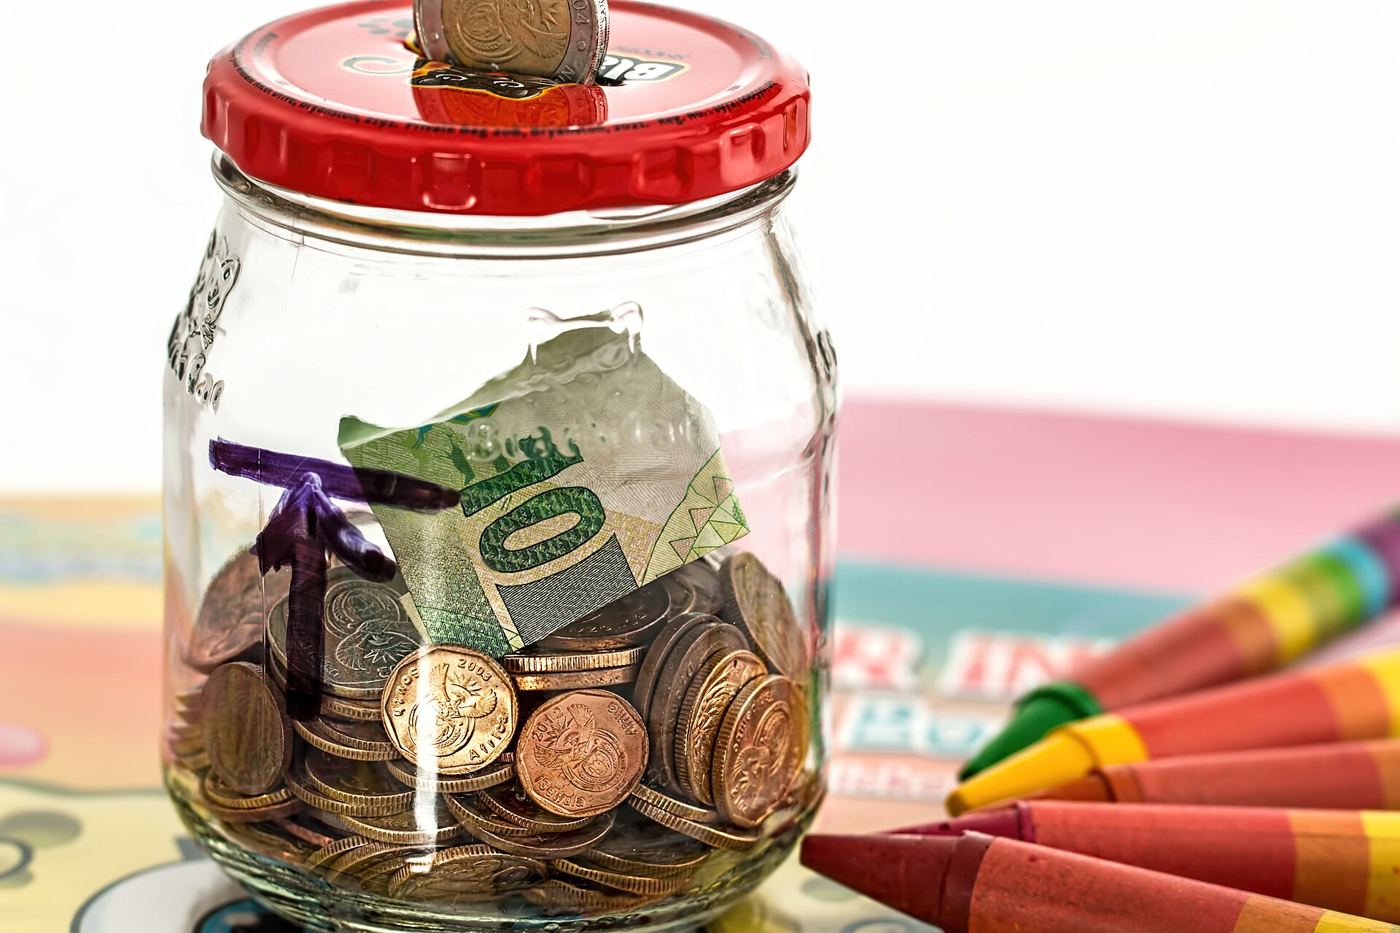
An emergency fund is money set aside for unexpected costs, such as a broken boiler, a car repair or a sudden loss of income, and it is one of the most practical steps in personal finance. Financial advisers commonly suggest holding three to six months of essential spending in an easy-access savings account, although even one month of cover is far better than none. The point is to avoid borrowing at high interest when life goes wrong, because credit card debt or payday loans can turn a small problem into a lasting one. An emergency fund also gives people room to make calm decisions, such as taking time to find the right job rather than accepting the first offer. It should be kept separate from everyday spending money, so that it is not used for holidays or treats, and it should be rebuilt after any withdrawal. Some people keep the fund in a separate bank account, which makes it harder to spend by accident on everyday purchases.
What the Evidence Shows
Building an emergency fund works best in small, automatic steps, such as moving a fixed amount into savings on payday before other spending begins. Many people start with a modest target, such as $500 or one month of rent, and then raise it gradually as income allows. High-interest savings accounts or money market funds are common choices, because the money stays accessible while earning some interest. The fund is not an investment, so chasing high returns is the wrong goal, and the money should not be tied up in shares or locked away for years. Households with irregular income, single earners or older cars and homes may need a larger cushion than others. Once the fund is in place, it quietly protects every other financial goal, from paying down debt to saving for retirement, by stopping emergencies from derailing the plan. Once the fund reaches its target, the same monthly amount can be redirected toward paying off debt or investing for retirement. Reporting and analysis from sources such as Financial Times track the same developments, and specialists following emergency fund households say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a financial system repricing risk after a long era of cheap money. Decisions shaped by emergency fund households are being made under closer supervisory attention, with stress tests and disclosure rules that assume conditions can worsen quickly. Institutions that planned for the benign case are adjusting in public, which is uncomfortable and healthy in equal measure.
What Happens Next
What happens next with emergency fund households will be visible first in the data that professionals watch weekly: flows, spreads and the terms on new deals. Participants who spoke for this article expect a period of adjustment rather than drama, with the biggest effects landing on those who assumed the old conditions were permanent. Planning, as ever, is the cheapest hedge. You can follow related developments in our coverage of finance.
None of this will be settled by a single announcement, study or product launch. The pattern to watch is accumulation: independent confirmations, honest reporting of failures and steady improvement in the underlying numbers. Readers who follow those signals, rather than the loudest claim of the week, will understand this subject better than most of the commentary surrounding it suggests is possible.
